Roof Financing in Torrance, CA
- 4.8★ from 73 Google reviews
- Free estimates
- Same day or next day service
- Photos of what we find
A roof is one of the larger bills a homeowner faces, and it rarely arrives on a convenient date. This page explains how financing generally works for a roof replacement and what to compare.
We are a roofer, not a lender, so we name no provider, rate or term here. The right product depends on your credit, your equity and the size of the job. Ask about financing at your free estimate, and we will tell you what we can arrange and what to compare.
How does roof financing work?
A lender pays for the roof, and you repay over time with interest and fees. The main types:
- Personal loan. Unsecured, fixed payments, usually a shorter term. Rates depend heavily on credit.
- Home equity loan or line of credit. Secured by your house, often at lower rates, with closing costs and a longer approval process.
- Cash-out refinance. A new mortgage that replaces the old one. It resets your whole loan, so it is a larger decision.
- Credit card. Fast, often costly if not repaid quickly.
- Contractor-arranged payment plan. Set up through the roofer and a lender. Convenient, but terms still need comparing.
None of this is personal financial advice. It is a map of what to ask.
What roof payment plans usually look like
A payment plan is a loan with a schedule: amount financed, annual percentage rate, term and fees. Two plans with the same monthly payment can cost very different totals, so ask for the total of all payments and compare it to the written estimate. Check for prepayment penalties and for promotional periods that change after a set time.
When does roof financing apply to your roof?
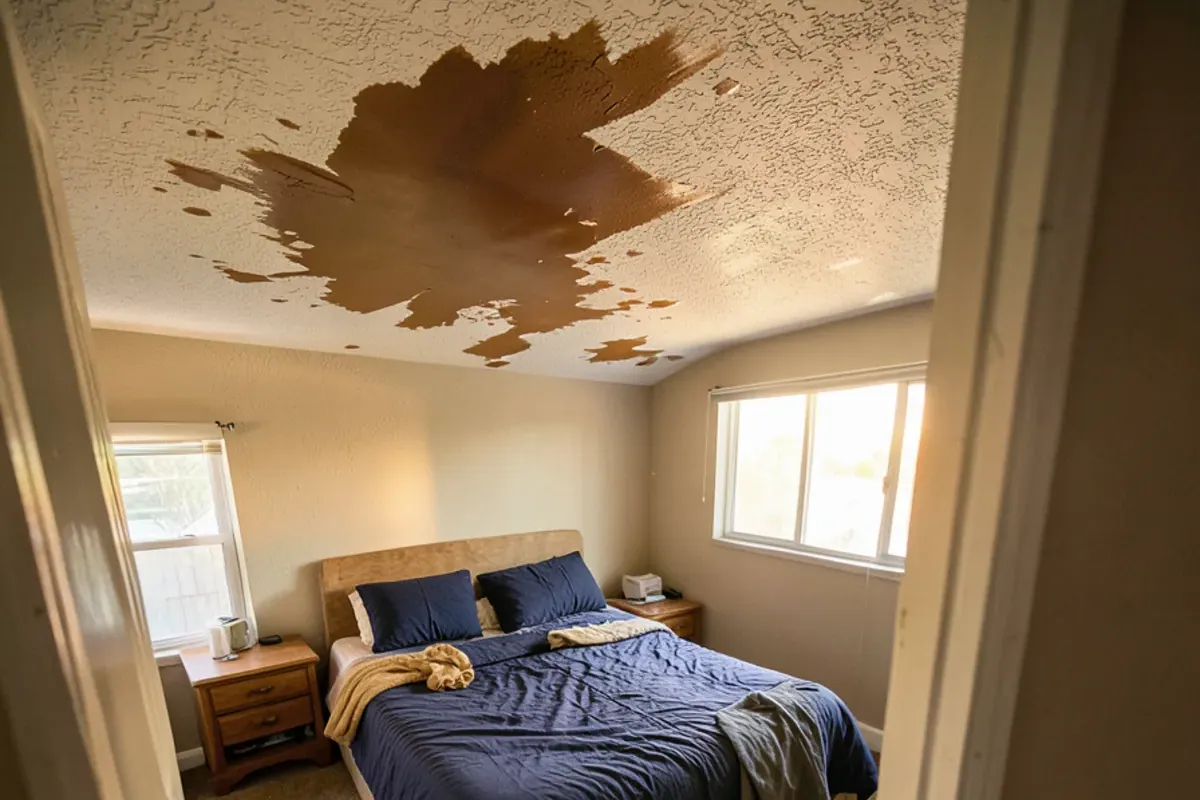
Financing questions usually arrive in one of three ways. A roof reaches the end of its life and the replacement is a planned project. A leak or storm forces a decision sooner than expected. Or an estimate shows deck damage that was not visible from the ground. In each case the useful move is the same: get the scope in writing first, then compare how to pay for it.
It rarely applies to a small fix. A cracked vent boot or a few lifted shingles sits in the repair range, and most owners pay that directly. Financing starts to matter when the quote involves tear-off, new underlayment or deck replacement, which is common on Torrance houses built around 1964 that are now on a second or third roof.
One Google reviewer described our communication as easy "from start to finish, including the job details, financing options, timeline, and any questions that came up along the way."
Can bad credit still get a new roof financed?
Sometimes, though choices narrow and costs rise. Lenders weigh credit score, income and debt. Secured products, which use your home, can open doors that unsecured loans do not, but they put the house at risk if payments stop. Ask for the full annual percentage rate and fees first. We cannot promise approval or a rate.
If the roof does not need full replacement yet, a repair may buy time; we repair first when a repair will do. Our roof tear-off and re-roofing pages explain each scope.
What was the HERO loan, and is it still an option for a California roof?
HERO was a PACE program. PACE repays an improvement through an assessment on your property tax bill rather than through a separate loan. Program availability, covered improvements and rules have shifted over the years, so ask whether any current PACE program covers roofs at your address. The assessment attaches to the property, and it can complicate selling or refinancing. Read the contract carefully. We do not provide or recommend a PACE program.
Should I finance the roof or wait for an insurance claim?
If a storm or a fallen tree damaged the roof, your homeowners policy may respond. That is between you, your insurer and, if you hire one, a licensed public adjuster. We document the damage with photos and can be on site for the adjuster's inspection. We do not negotiate claims. You pay your deductible.
If a leak is active, do not let a pending claim leave the roof exposed. See roof insurance claims.
How we price the job
We do not post prices. For context only: published cost guides in 2026 place most roof repairs between $300 and $1,500, and one listing (Homeyou, 7,210 projects, 2026) puts the average Torrance roof replacement at about $7,202 to $8,183. That is market data, not our quote. The price you finance depends on:
- Roof size, pitch and number of layers to remove
- Material, such as shingle, tile or metal
- Deck repairs found at tear-off
- Flashing, vents and permit details
- Extras like gutters, skylights or solar detach and reset
Which California contract and licensing rules apply to a financed roof?
California limits the down payment a contractor can ask for on a home improvement contract. The Contractors State License Board publishes the current limit, so check it before you sign. Check any roofer's license on the CSLB site before agreeing to a payment schedule.
Other state rules protect you at the contract stage. The CSLB explains that a home improvement contract must be in writing and include the scope, price, payment schedule and start and completion dates. It also describes a short right to cancel for many contracts signed at your home, and the window differs for seniors. Confirm the current terms on the CSLB site. These rules apply to the roofing contract. A loan has its own paperwork, so read that separately.
What a free estimate includes, and the steps to get one
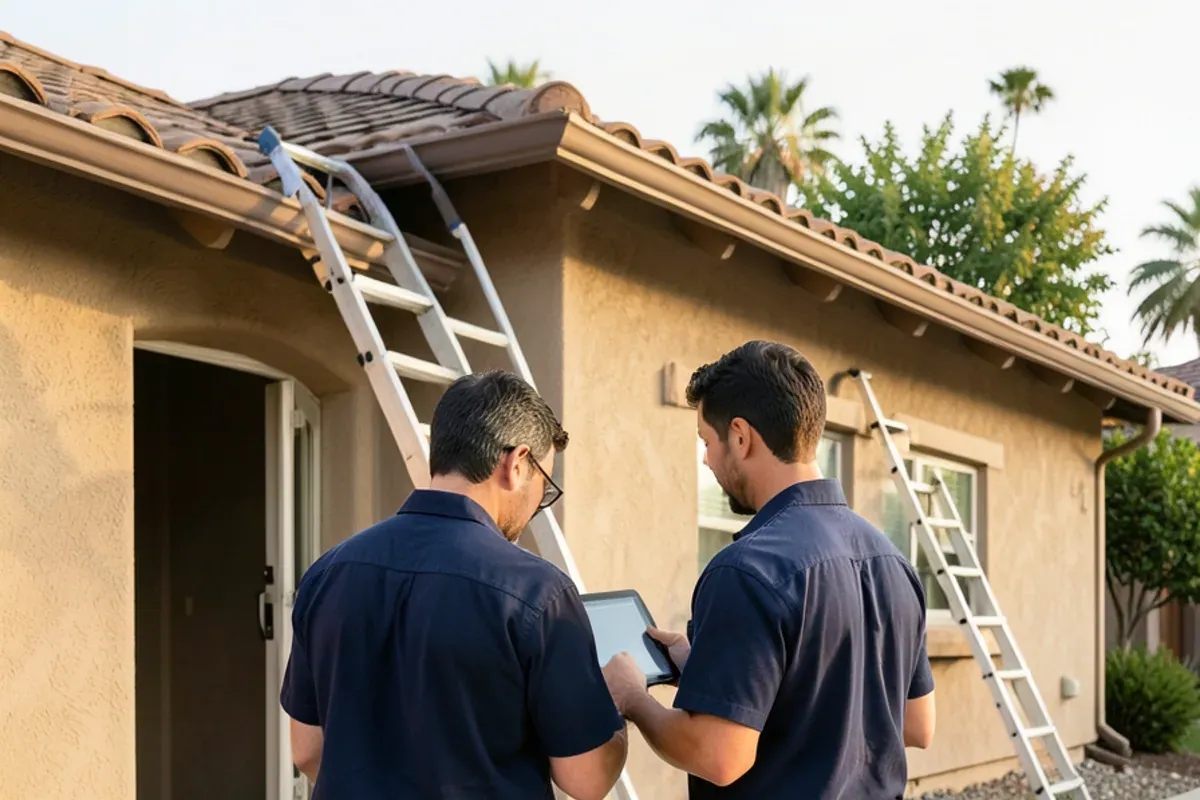
Financing is only worth comparing once you know what the roof job covers, so the estimate comes first. We walk the roof, look into the attic where access allows, and separate repair from replacement. You see the same photos we see. Any loan or plan then gets compared against a number you understand. The estimate includes these deliverables, before any financing talk starts:
- A roof and attic inspection, with photos of what we find
- A written scope that separates repair options from replacement options
- Material choices, with shingle samples where they apply
- Permit details and a realistic schedule
- A plain explanation of where financing fits, without a provider, rate or term decided for you
The steps:
- Call and book a free roof inspection. We offer same day or next day visits.
- We inspect the roof and attic and show you photos of what we find.
- You receive a written estimate with repair and replacement options explained in plain terms.
- Tell us you want to discuss financing, and we go through what we can arrange.
- Compare any offer with others, including your own bank or credit union, before you sign.
Why Crown Trim for a financed roof?
- Reviewers rate us 4.8 stars across 73 Google reviews.
- Free estimates and roof inspections.
- We explain your options in plain terms and put the scope in writing.
- We repair first when a repair will do.
- We handle permit details on re-roofs, protect landscaping and driveways, and clean up thoroughly.
We serve homeowners across the South Bay, including Carson, Redondo Beach and Rancho Palos Verdes. For a wider look at the money side, see roof replacement cost in Torrance.
Where we do roof financing around Torrance
Each place brings its own version of this job.
- Lakewood: Early-1950s ranch homes of the same age reach re-roof time together, so owners compare a financed full replacement against patching a few more years.
- Montclair: Montclair's 1950s-60s tract homes are at the age where full re-roofs come up, so ask about financing at your estimate.
- Lomita: Post-war bungalows with worn composition roofs sit a few minutes from our base, so a free inspection and a written scope come before any payment talk.
- Bellflower: Small ranch homes and courtyard apartments along Bellflower Boulevard put owners of both houses and small multi-unit buildings in the position of weighing payments.
- Downey: Large post-war ranch homes have big roofs, and a bigger roof means a bigger total to compare across loan terms.
- Gardena: Post-war homes and small low-slope commercial lots mix here, so the job size, and the way people pay for it, varies from a repair to a full roof.
- Long Beach: Period homes in Bixby Knolls and California Heights, plus port-side commercial buildings, cover repair-sized to project-sized work.
- South Gate: 1920s to 1940s bungalows and post-war homes often have layers to remove and deck repairs, which can move a quote into financing territory.
- Rancho Palos Verdes: Hillside access, ocean wind and fire-rated roof details add to a replacement total, so owners often ask about payment options early.
- Inglewood: 1920s to 1950s houses and apartment blocks near the stadium district include owners deciding between staged repairs and one larger roof project.
What customers say about this work
Crown Trim Roofers holds 4.8 stars from 73 Google reviews. Read all reviews
“Communication was easy from start to finish, including the job details, financing options, timeline, and any questions that came up along the way.”
“The new roof looks excellent, and we feel much better knowing our home is protected during the windy and stormy times of year in Torrance.”
“In just a couple of hours, they finished the long-lasting repair, cleaned everything up, and showed me pictures of the work they did.”
Roof Financing: common questions
What financing options are available for a new roof in Torrance?
Homeowners generally choose among a personal loan, a home equity loan or line of credit, a cash-out refinance, a credit card, or a payment plan arranged through the roofer. Each has different costs and risks. We do not name a provider, rate or term here. Ask about financing at your free estimate and compare any offer in writing.
Can I finance a roof repair as well as a full replacement?
Often yes, though small repairs are usually cheaper to pay outright than to finance. Published cost guides in 2026 place most roof repairs between $300 and $1,500. Larger jobs, such as a deck rebuild or full replacement, are where payment plans come up most. Ask at the estimate what options fit the size of your job.
Should I finance the roof or wait on an insurance claim?
That is your decision, and it depends on your policy. If damage came from a sudden event like a storm, a claim may apply, and you pay your deductible. We document damage with photos and can be on site for the adjuster's inspection, but we do not negotiate claims. See roof insurance claims.
Can I get roof financing with bad credit?
Options narrow and costs usually rise as credit scores fall, but lenders differ, so a no from one place is not a no from all. We cannot promise approval. Ask a lender for the full annual percentage rate and fees, and consider whether repairing the worst areas now and replacing later makes sense.
What is a HERO loan, and can I use it for a roof in California?
HERO was a PACE program, where a property tax assessment repays the cost over time. PACE availability and the improvements it covers have changed, so ask whether any current program covers roofs. An assessment can complicate a home sale or refinance, so read the contract closely. We do not provide or recommend a specific program.
How does a monthly payment compare with the total roof cost?
A lower monthly payment usually means a longer term and more interest paid overall. Ask any lender for the total of all payments, not just the monthly amount. Then compare it with the written roof estimate. Our post on roof financing options for California homeowners walks through this.
Related services and guides
Roof Tear-Off & Removal
Re-Roofing (Overlay)
Roof Financing Options for California Homeowners
Roof Replacement Cost in Torrance: What Drives the Price
What Tile Roof Underlayment Replacement Costs and Why
Where we work: Carson, Redondo Beach, Rancho Palos Verdes, Gardena and the rest of our service areas.
Need a payment plan? Ask about financing at your estimate.
Call first. A roofer picks it up from there.