Roof Insurance Claims in Torrance, CA
- 4.8★ from 73 Google reviews
- Free estimates
- Same day or next day service
- Photos of what we find
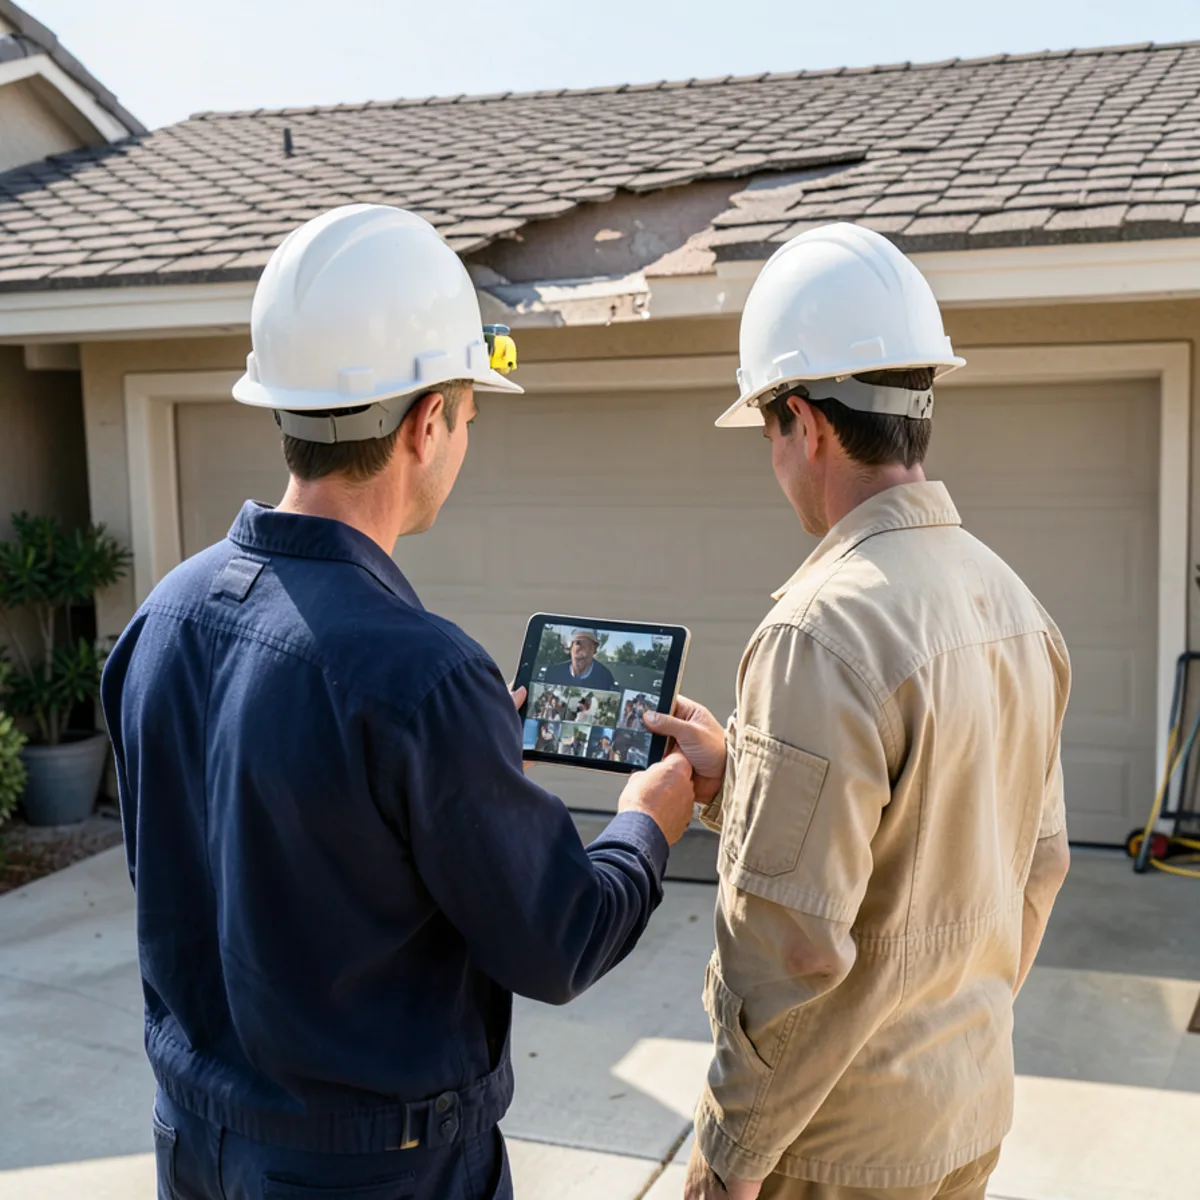
A claim is a paperwork process built on a physical event, and the roof is where the evidence lives. We handle the roof side: photos, scope and attendance. You, your policy and your insurer handle the coverage side. This page sits inside our emergency roof repair service. If water is already coming in, start with emergency roof tarping, and for the damage itself see storm damage roof repair.
What does our part in a roof damage insurance claim include?
Our role is narrow on purpose: the physical roof and the paperwork that describes it, stopping where coverage decisions begin. The scope of our claim support includes:
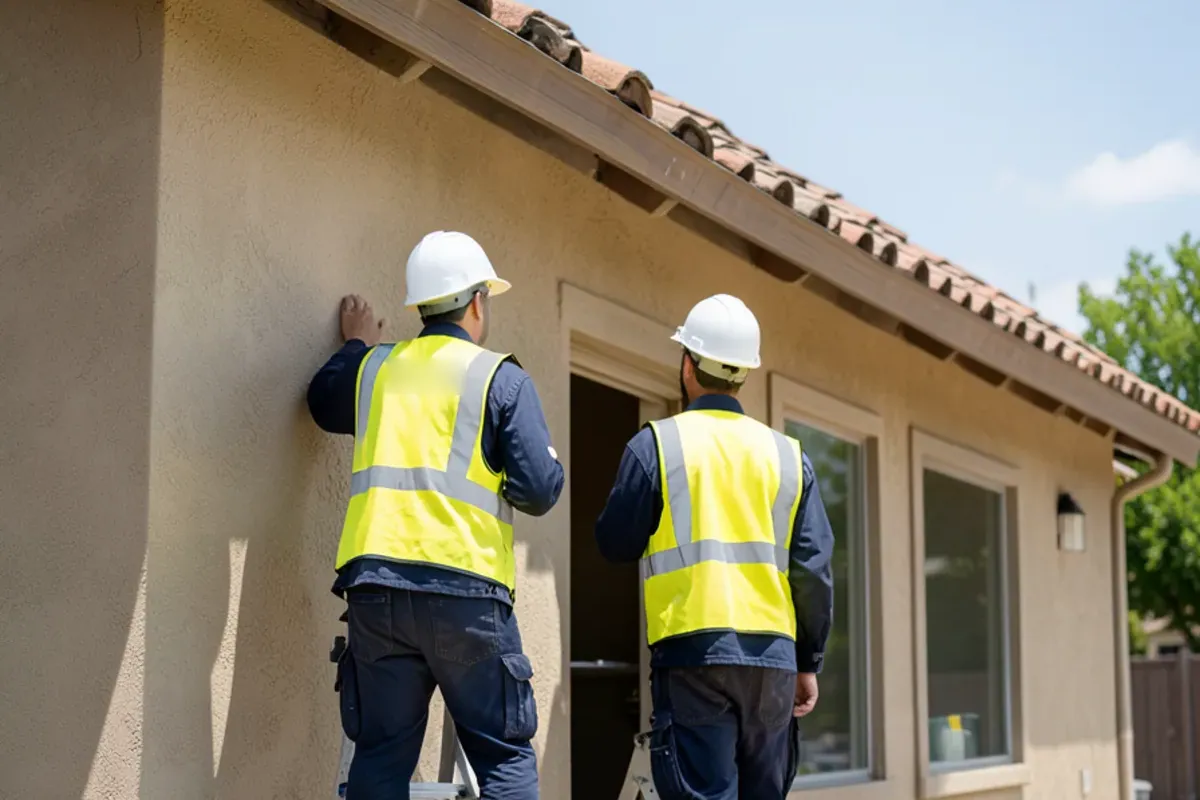
- Inspect the roof and attic for damage and its likely cause
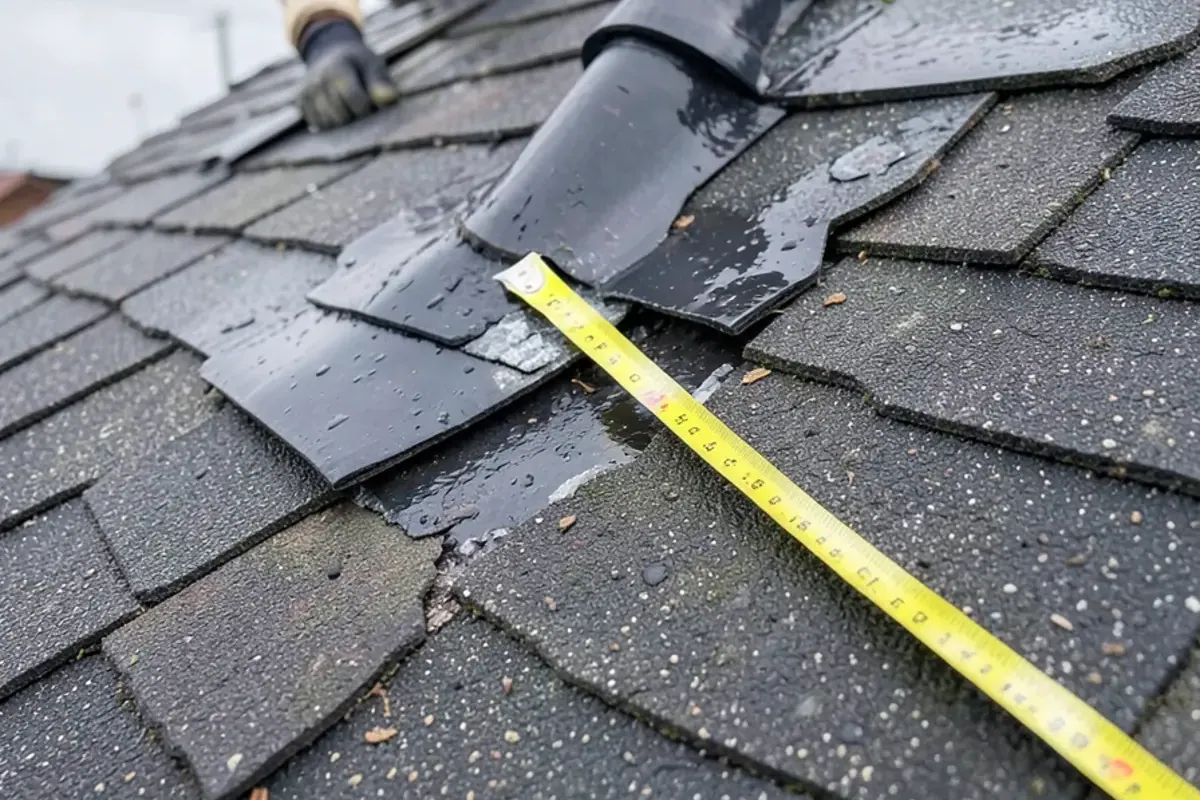
- Photograph the damage with close and wide shots, with scale references
- Explain repair and replacement options in plain terms
- Write the estimate so the scope is clear
- Be on site for the adjuster's inspection when you want us there
- Handle permit details when the work is a re-roof
What we do not do: negotiate a claim, advise on coverage, tell you whether to file or act as an adjuster. In California, only the policyholder or a licensed public adjuster negotiates a claim.
What counts as roof damage, and what signs show it is recent?
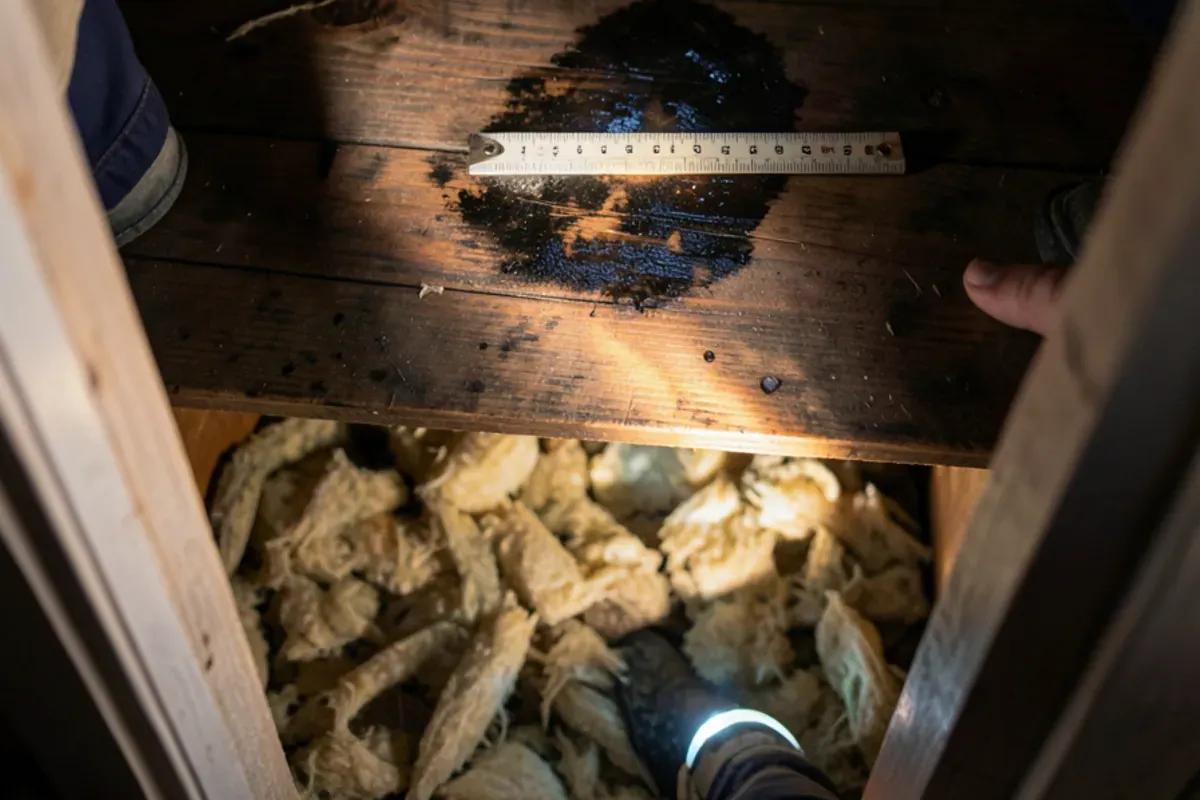
Claims usually start with a sudden event, not slow aging. In Torrance that means a winter atmospheric river that drives rain under lifted shingles, a Santa Ana wind that strips ridge caps or tile, or a limb or tree that lands on the roof. Fresh signs include creased or missing shingles, cracked or slipped tile, bent flashing, dented vents, new ceiling stains and wet attic insulation after the event.
Gradual wear looks different: curled edges across a whole slope, granule loss and brittle material on a 1960s roof. Policies treat the two differently, and wording varies, so your policy and your insurer decide what is covered. Our part is to record what the roof shows, in dated photos, so the picture is accurate whichever way the decision goes. If you are unsure whether damage is recent, have the roof inspected before repairs change the evidence.
How do you document roof damage before the adjuster comes?
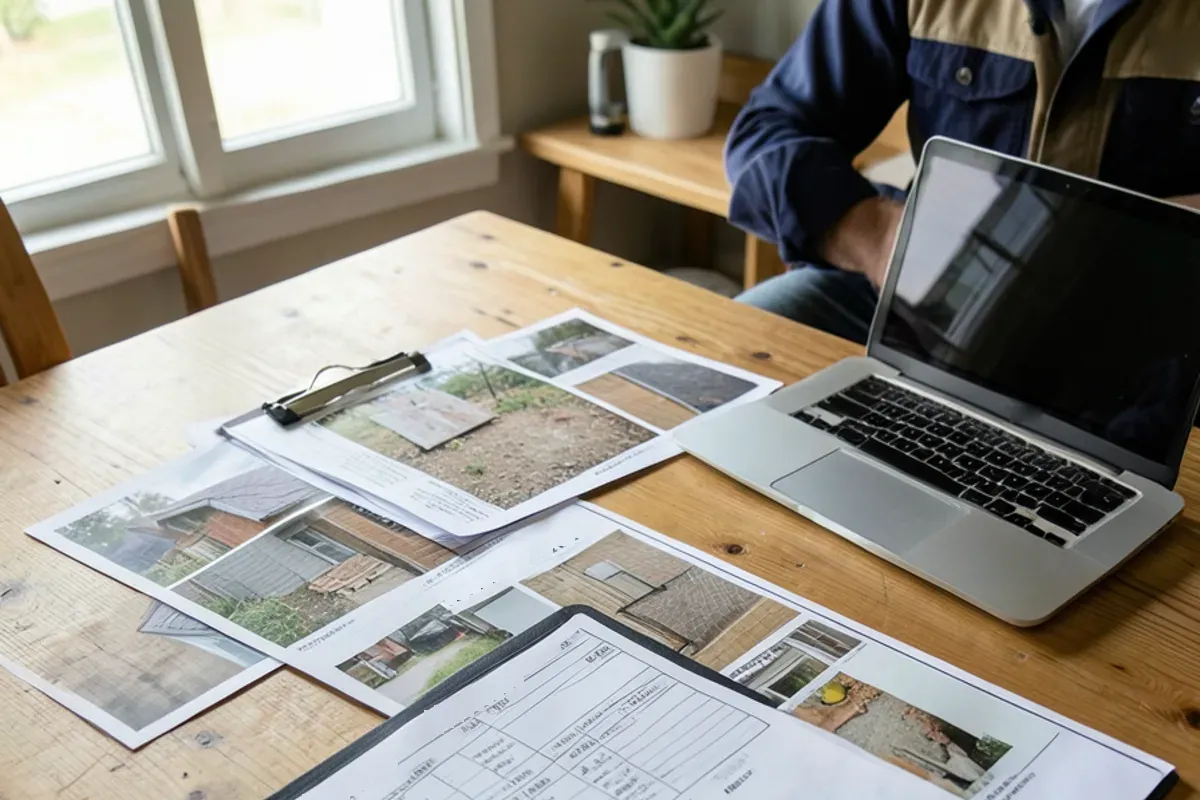
Good documentation is the cheapest part of a claim. Do these before and while we are there:
- Photograph the ground first: debris, fallen shingles, damaged fences and gutters, with dates.
- Photograph the interior: ceilings, walls, floors and damp attic insulation.
- Keep damaged materials in a pile if it is safe to do so.
- Note when the storm or event happened and when you first saw damage.
- Keep receipts for any temporary protection, such as a tarp.
- Let us photograph the roof surface, so you do not climb up.
One Google reviewer said the roofer "came out during the insurance inspection so all the roof damage and exterior issues were properly noted." Noting the damage is the point.
Can a roofer meet the adjuster during the inspection?
Yes, and it often helps. A roofer who has already been in the attic can point out the spots that matter: the soft decking, the creased shingles on the far side, the flashing that pulled loose. We bring our photos and answer technical questions about the roof.
What we do not do is argue coverage. If the adjuster says something is not covered, that is a conversation between you and your insurer. If you want help with it, a licensed public adjuster is the professional for that.
Ask your insurer to confirm the date and that a contractor may attend.
Insurance roof replacement in Torrance: repair or replacement, and who decides
Many claims end in a repair, not a new roof. A repair fits local damage, such as a few creased shingles or a valley. One Google reviewer, whose claim was hard to deal with, said the roofer gave "an honest estimate" and explained that the main issue was in the roof valley, not the whole roof system. That is the kind of scoping we do.
Replacement becomes reasonable when damage is widespread, materials are too brittle to repair or matching is not possible. Your insurer makes its own determination. Our job is to show the roof's condition honestly, with photos. We do not push a full replacement.
What if the insurer misses roof code upgrades?
Roof work needs a permit, and the building department decides what current code requires for your address. In Torrance, that is City of Torrance Building & Safety. Confirm requirements for your address at (310) 618-5910. Unincorporated areas use LA County Public Works, and the City of LA uses LADBS.
Code can require items that were not on the roof when it was built, such as different underlayment, flashing or, in some cases, other changes. We list what the permit and repair will require in our estimate. Whether your policy pays for code upgrades depends on its wording, so ask your insurer before the work. If the adjuster's scope leaves out a required item, send the insurer our documentation and ask for a supplement. Whoever does the work, check the contractor's license on the California Contractors State License Board site, since state law requires one for most jobs over $1,000.
What can you do if a roof claim is denied in California?
Steps policyholders commonly take after a denial:
- Ask for the denial in writing, with the policy language cited.
- Compare it with your photos and our inspection findings.
- Send new evidence and request a reconsideration.
- Check whether your policy includes an appraisal process for disputed amounts.
- File a complaint with the California Department of Insurance if you think the claim was mishandled.
- Consult a licensed public adjuster or an attorney.
Our post on what to do if a roof claim is denied goes through the options. We can provide photos, but we cannot argue the claim for you.
Roof insurance claim costs and your deductible
The estimate is free. We do not post prices, and we do not set what your insurer pays. For context, 2026 published cost guides place most roof repairs between $300 and $1,500, and a Torrance roof replacement averages about $7,202 to $8,183 (Homeyou, 7,210 projects, 2026 listing). Those are market data, not quotes. The scope depends on how much roof is damaged, the material, the pitch, wet decking or insulation and what the permit requires.
Is it legal for a roofer to pay your deductible?
You pay your deductible. We do not waive it, absorb it or rebate it, and we do not offer to. Watch for this in any contractor. For the rules that apply to you, contact the California Department of Insurance and read your policy. A roofer who promises you a free roof or "no out-of-pocket cost" is making a promise that your insurer, not the roofer, controls.
Why Crown Trim for claim documentation
- Free roof inspections and estimates, with photos of what we find so you hold your own record.
- We document damage with photos and can be on site for the adjuster's inspection.
- We explain repair and replacement options in plain terms, and we do not push a full replacement.
- We handle permit details on re-roofs.
- Same day or next day service when the roof is open, with temporary cover first.
- Thorough cleanup, protecting landscaping and driveways.
- Reviewers rate us 4.8 stars across 73 Google reviews.
We document roof damage in Carson, Redondo Beach and Rancho Palos Verdes, and in Torrance. Cities differ on who issues roof permits, so confirm the building department for your address. Our guide on how to file a roof insurance claim in California covers the steps in order.
Where we do roof insurance claims around Torrance
Each place brings its own version of this job.
- Palos Verdes Estates: Red clay tile and Art Jury review make matching and scope questions common, so close photos of existing tile help the record.
- Rancho Palos Verdes: Ocean-facing roofs with wind, salt and slope movement near Portuguese Bend need dated photos to separate storm damage from long-term wear.
- Redondo Beach: Salt-air corrosion sits beside storm damage on beach bungalows and condos, so documentation shows which is which.
- Agoura Hills: Woolsey Fire history on hillside tile tracts makes photo documentation valuable, and we can be on site for the adjuster's inspection.
- Rolling Hills Estates: Long ranch roofs on horse-property lots have large slopes to photograph, and the damage may sit across several planes.
- Bell Canyon: The 2018 Woolsey Fire destroyed homes here, so we document roof damage with photos and can attend the adjuster's inspection.
- Carson: Aged tract-home roofs from the 1950s and 60s raise roof-age questions in a claim, so condition photos matter.
- Lomita: Bungalows with old layered roofs mean the adjuster and roofer may need to see through to decking from the attic.
- West Carson: Unincorporated homes follow LA County permits, so code-upgrade questions go to the county rather than to Torrance or Carson.
- Gardena: Post-war homes and small low-slope commercial buildings both file roof claims, with different scopes and documentation.
What customers say about this work
Crown Trim Roofers holds 4.8 stars from 73 Google reviews. Read all reviews
“He also handled the issues that came up with my insurance claim, which took a lot of stress off me.”
“After several heavy summer rainstorms, it has been a huge relief not to worry about leaks anymore.”
“When my roof was damaged during a wind storm, I needed a full replacement.”
Roof Insurance Claims: common questions
Can a roofer meet my adjuster during the inspection?
Yes. We can be on site for the adjuster's inspection so the roof, attic and exterior damage are pointed out and noted. We bring our photos. We do not negotiate the claim or speak for you on coverage. Only the policyholder or a public adjuster who holds a state license does that. Ask your insurer to confirm the date and that a contractor may attend.
What if the insurance company misses needed code upgrades on my roof?
Roof work needs a permit, and the building department decides what current code requires for your address. We document the requirements that apply to the repair and show them to you in the estimate. Whether your policy pays for code upgrades depends on the policy, so ask your insurer. The City of Torrance Building & Safety office is at (310) 618-5910.
What can I do if my roof claim is denied?
Ask the insurer for the denial in writing, with the policy language it relies on. Gather your photos, repair estimates and any new evidence, then request a reconsideration. You can also file a complaint with the California Department of Insurance, consult a licensed public adjuster or speak with an attorney. We can provide photo documentation of the roof's condition.
Is it legal for a roofer to pay my deductible in California?
You pay your deductible, and we do not waive, absorb or rebate it. We will not offer to cover it, discount around it or promise you a free roof. For the legal rules, contact the California Department of Insurance and read your policy. A roofer who offers to make the deductible disappear is a reason to pause and ask questions.
Will you start repairs before the adjuster arrives?
We protect the roof first, because water damage grows quickly, and we photograph everything before and after. Permanent repair usually waits until the adjuster has seen the damage, unless safety requires otherwise. Keep any removed material if your insurer asks for it. Tell the insurer what temporary steps you took.
Related services and guides
Emergency Roof Tarping
Storm Damage Roof Repair
Does Homeowners Insurance Cover Roof Leaks in California?
How to File a Roof Insurance Claim in California
Roof Claim Denied? Your Options in California
Where we work: Carson, Redondo Beach, Rancho Palos Verdes, Gardena and the rest of our service areas.
Roof damage and a claim ahead? Get it documented first.
Call first. A roofer picks it up from there.